 How-to
How Do You Negotiate Interest Rates on Car Loans?
Last Updated: October 26, 2026
Quick Summary
Car loan negotiation means competing offers instead of accepting the dealer's first rate: get preapproved with a bank, credit union, and online lender, then ask the finance office to match or beat that APR. Negotiate the vehicle price, trade-in, and financing separately, and get the APR and total interest in writing before you sign.
- A dealer can stretch your loan term to lower the monthly payment while raising your total interest.
- Compare the APR and total interest on every offer, not the monthly payment.
- Settle the out-the-door price first, then trade-in value, then financing, then add-ons.
- Ask the finance manager whether the quoted rate is the buy rate or includes dealer markup.
- Refinance when your credit score improves or the new rate beats your current APR by enough to cover fees.
Table of Contents
- Why the Interest Rate Matters More Than the Monthly Payment
- Get Preapproved Before You Set Foot in a Dealership
- How to Compare Auto Loan Offers Side by Side
- Car Loan Interest Rate Factors That Decide Your APR
- A Car Loan Negotiation Script for the Finance Office
- When to Refinance a Car Loan After You Sign
- Get Pre-Qualified With Buy & Buy Auto Sales
- Frequently Asked Questions
Why the Interest Rate Matters More Than the Monthly Payment
The average monthly payment for a new vehicle hit $765 in the second quarter of 2026, according to LendingTree's auto debt statistics. That number grabs attention. But the monthly payment is the wrong number to fixate on.
Here is the trap. A dealer can stretch your loan term to lower the monthly payment while raising the total interest you pay.
The rate decides three things:
- Your total interest charges
- How much of each payment goes to principal
- How much car you can truly afford
A lower rate cuts your total loan cost without changing the vehicle price by a single dollar.
Get Preapproved Before You Set Foot in a Dealership
Preapproval is your strongest lever. It turns you from a shopper hoping for a good rate into a buyer with a known number in hand.
A preapproved auto loan is a lender's written offer to finance your purchase up to a set amount at a set rate.
Here is how to get it done:
- Pull your credit reports and check for errors
- Apply with a bank, a credit union, and one online lender
- Compare the APR on each offer, not the monthly payment
- Get the preapproval letter in writing with an expiration date
Walk in with that letter and you have a benchmark. Any dealer financing has to beat it, or you use your own. Our guide on how to get pre approved for a car loan in 2026 walks through each step.
How to Compare Auto Loan Offers Side by Side
Comparing offers means lining up the same loan terms across lenders and looking at APR and total cost, not the payment. A lower payment on a longer term can cost you more.
Use this checklist for every offer you collect:
| What to Compare | Why It Matters |
|---|---|
| APR | Includes rate plus fees; the true cost |
| Loan term | Longer terms lower payments but raise total interest |
| Down payment | More down means less principal borrowed |
| Lender fees | Origination or processing fees raise your real cost |
| Total interest | The full dollar amount you pay to borrow |
| Prepayment penalties | Fees for paying off early block savings |
The average rate gap is wide. According to Experian's auto loan data, the average rate was 6.35% for new cars and 11.19% for used cars. A few points of APR on the same balance adds up fast. For a deeper breakdown, see our guide on dealership financing vs bank loans.
Car Loan Interest Rate Factors That Decide Your APR
Your APR comes from your credit profile, the loan term, the vehicle, and the lender. Understand each factor and you know where you have room to push, and where you are wasting effort.
Credit score is the biggest lever. It sets your risk tier and your rate. Credit history length and payment record matter too. A thin file can mean a higher rate even with no late payments.
Other factors that move your rate:
- Loan term: shorter terms usually carry lower rates
- Down payment: more cash down lowers lender risk
- New vs. used: used cars typically carry higher rates
- Vehicle age and mileage: older cars cost more to finance
- Debt-to-income ratio: high debt raises your rate
Rates can run from below 5% APR to above 21% APR depending on the borrower, per The Wall Street Journal's rate overview. Our breakdown of a good interest rate for used cars gives you a benchmark.
How the factors interact
These levers are not independent. A longer term lowers your payment but usually raises your APR, so total interest can climb even as the monthly number falls. A larger down payment lowers the amount financed and can also nudge you into a better loan-to-value tier, which lowers the rate itself.
That interaction is why comparing offers on payment alone fails. Two offers with the same payment can carry very different APRs and total costs.
What each credit profile can actually do
The general advice to "improve your credit score" is useless in the finance office today. Here is what actually moves the needle by profile:
- Excellent credit (roughly 781+): You have leverage. Get preapproved with a credit union, then ask the dealer to beat it. Focus on term, a shorter term at your rate saves the most.
- Good credit (roughly 661-780): Shop at least three lenders. A quarter-point spread on a $30,000 loan is real money. Ask about relationship discounts and automatic-payment discounts.
- Fair credit (roughly 601-660): Expect a higher rate. A larger down payment is your best rate-lowering tool because it reduces lender risk. Consider a newer used car rather than an older one.
- Poor or rebuilding credit (below roughly 601): Traditional banks may decline you. Credit unions and buy-here-pay-here dealers are the realistic path. Focus on getting approved at a rate you can afford, make six to twelve on-time payments, then refinance.
- Thin file (limited history): A cosigner with strong credit can move you into a better tier. Otherwise, a larger down payment and a less expensive vehicle reduce the lender's exposure.
The vehicle itself is a rate factor
Lenders price the collateral, not just the borrower. Older cars and high-mileage vehicles carry higher rates because they are harder to repossess and resell. A vehicle that is a few years old with lower mileage often finances cheaper than a similar-priced older model. If you are rate-sensitive, let the vehicle choice work for you.
A Car Loan Negotiation Script for the Finance Office
A car loan negotiation script is a set of prepared lines you use in the finance office to ask for a lower rate and better terms. It keeps you calm and on message when the pressure hits.
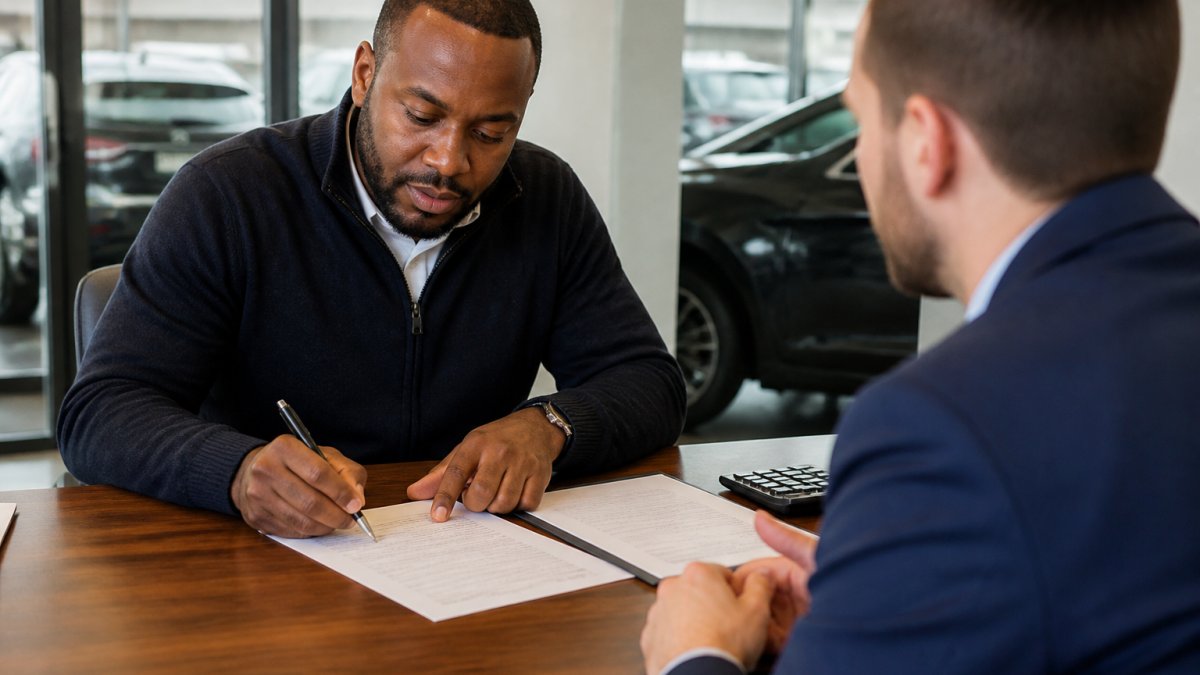
The finance office is where the real terms appear. A 2020 Georgetown Law Journal article by A. J. Levitin describes buyers learning financing terms only after negotiating price, trade-in, warranties, and insurance.
Know what you are actually negotiating against
Before you say a word, understand the dealer's side of the table. A dealer does not lend you money, it shops your application to lenders and then presents a rate. Lenders approve a buy rate, the wholesale rate the dealer is charged.
That is why the most important question in the room is not "What's my payment?" It is "What is the buy rate, and what is the markup?" Most finance managers will not hand you the buy rate, but asking signals you understand the mechanics and shifts the conversation from payment to price of money.
The order of negotiations
Negotiate in this sequence and never let the dealer bundle the steps:
- Vehicle price, settle the out-the-door price first, in writing.
- Trade-in value, negotiate it as a separate number, not as a payment offset.
- Financing, only now discuss APR, term, and down payment.
- Add-ons, decline or negotiate warranties, gap insurance, and paint protection last, after the loan terms are locked.
Dealers profit from collapsing these steps into one monthly payment. Keeping them separate is the whole game.
Lines that work
Use these verbatim, and pause after each one. Silence is a tool.
- "I'm not ready to talk payment yet. Let's settle the out-the-door price on the car first."
- "What is the APR on this offer, and what is the total interest over the full term?"
- "I have a preapproved offer at a lower rate. Can you match or beat it?"
- "Can you show me the same loan at a shorter term?"
- "Is this rate the buy rate, or does it include dealer markup?"
- "I want to negotiate the vehicle price and the financing separately."
- "Please put the APR, term, amount financed, and total interest in writing before I sign anything."
Handling the counteroffer
When the finance manager comes back with a number, do not accept or reject on the spot. Run this loop:
- Ask for the breakdown. "Can you show me how you got to that APR, rate, fees, and term?"
- Anchor to your preapproval. "My credit union is at X%. I'll finance here if you can get within a quarter point."
- Trade term for rate, not payment. If they will not move the APR, ask for a shorter term at the same rate to cut total interest.
- Walk if the numbers do not move. A preapproval means you have a real alternative. Use it.
Pair this with our tactics on how to negotiate car price at dealership.
When to Refinance a Car Loan After You Sign
Refinancing replaces your current auto loan with a new one at a lower rate. It is worth it when the new rate beats your current APR by enough to cover any fees and still save money.
Signs it may be time:
- Your credit score improved since you bought
- You were offered a high rate at the dealership
- Rates dropped since you financed
- You want a shorter term to cut interest
Delinquencies are rising, which makes lenders cautious. According to Federal Reserve Bank of New York data cited by Snell & Wilmer, 90-day auto loan delinquencies reached 5.60% in the first quarter of 2026, up from 5.21%. If you are weighing options, our overview of best financing options for used cars covers what to compare.
Get Pre-Qualified With Buy & Buy Auto Sales
Negotiating a rate takes use, and use starts with knowing your options.
We offer financing options regardless of credit history, with no hidden fees and down payment flexibility. You can get pre-qualified in minutes. Flexible terms let you pick a loan that fits your budget instead of one that just fits the monthly payment. That is the stress-free, hassle-free buying experience we aim for.
The rate you accept today follows you for years. Get pre-qualified with Buy & Buy Auto Sales.
Frequently Asked Questions
How do I negotiate a lower interest rate on a car loan?
Start with a preapproval from a bank or credit union so you walk in with a competing offer in hand. Ask the dealer whether they can beat that rate, and get the answer in writing. Compare the APR, not just the monthly payment, and check the loan term and fees. The Consumer Financial Protection Bureau notes borrowers can ask dealers directly whether better terms are available or cite lower rates found elsewhere.
Is it better to get preapproved before negotiating a car loan?
Yes. A preapproval turns an abstract request into a concrete comparison. You know your rate, term, and maximum loan amount before you discuss financing, giving you a real number to use as a comparison. It also separates the vehicle price negotiation from the financing negotiation, so each part of the deal gets its own attention.
What credit score do I need to get a lower car loan rate?
There is no single cutoff, but rates move sharply with credit profile. Experian reported average rates of 6.35% for new cars and 11.19% for used cars, while 2026 rate surveys showed offers ranging from below 5% APR to above 21% APR depending on the borrower. Checking your credit report for errors and paying down balances before you apply can move you into a better tier.
Can refinancing lower my car loan interest rate?
It can, especially if your credit has improved since you signed or if you accepted a dealer-arranged rate without shopping around. Compare the new APR against your current one and factor in any fees and the remaining loan balance.